Four | Buy Now, Pay Later

- 5.44K Reviews
- 4.4
- Downloads
- 1,000,000+
Our take on Four | Buy Now, Pay Later from Appgk
Four is a shopping app from Four Technologies, Inc built around a simple idea: buy something online now and divide the payment into a schedule that feels easier to manage. I approached it as a first-time shopper rather than someone already familiar with buy-now-pay-later services, and that changed what stood out to me. The important part is not merely seeing a payment option at checkout; it is understanding the commitment before confirming it.
The app is free to download and is aimed at everyone, with support for devices running Android 6.0 or later. It sits in the shopping category, but it does not work like a normal marketplace where you browse a large catalog and place every order inside one storefront. Its value appears when Four is available as a payment choice during an online purchase. That distinction matters because your experience depends heavily on whether the retailer supports it and whether the purchase fits the service’s approval and payment flow.
Four has reached more than a million installs and holds a 4.4 average from around thirteen thousand ratings, with roughly five thousand reviews. Those figures suggest that the basic idea is easy for many shoppers to understand, although they should not be mistaken for a guarantee that every order or retailer will feel equally smooth. My overall impression is that Four can be useful for planned purchases, but it rewards careful reading much more than impulsive tapping.
Getting from installation to a useful first purchase
What to expect before you begin
The first thing I would tell a new user is to think of Four as a payment-planning tool rather than free money. Splitting a purchase can make a larger expense easier to organize, but the total obligation still exists. Before opening the app, I would decide what item I actually need, how much I can comfortably commit to, and whether I can keep track of several scheduled payments alongside normal bills.
Best Parts of Four | Buy Now, Pay Later
Things to Keep in Mind About Four | Buy Now, Pay Later
This mindset prevents the most common mistake: treating a smaller first payment as the true cost of the item. The app’s appeal is flexibility, not a discount. If you already know that a purchase would strain your budget when viewed as a whole, dividing it does not solve that underlying problem. I found the service most sensible when used for a planned household item, clothing purchase, or replacement product that I had already budgeted for.
There is also a practical difference between shopping through a familiar retailer’s checkout and expecting Four to behave like a universal payment button everywhere. A retailer needs to offer the service, and the available path may vary. I would therefore check for Four at the payment stage instead of assuming it will appear simply because the app is installed.
News and Features Related to Four | Buy Now, Pay Later

News
YouTube Turns a Quick Video Check Into an Hour of Watching

News
BeautyPlus Makes Portrait Retouching Feel Like Your Own

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo
That small habit saves time. It also encourages you to compare the final payment schedule with the retailer’s ordinary payment methods. A standard card payment is simpler when you can comfortably pay in full. Four becomes more interesting when spreading the cost helps you align the purchase with your cash flow without losing sight of the full amount.
Setting up an account without rushing
After installing the app, I would use the setup process slowly and read each screen before continuing. The useful goal is not to finish registration as quickly as possible; it is to reach the point where you understand how Four presents an order, the payment timing, and any conditions attached to that purchase. A few extra seconds here can prevent confusion later.
Don't want to read the full review?
Keep the details you use consistent and make sure you can access the payment method connected to the purchase. If you are shopping from a phone, it is easy to move between the retailer, Four, and a banking app while losing track of which screen is showing the final arrangement. My practical tip is to pause after each confirmation and identify three things: the item being purchased, the total commitment, and the next payment event.
Do not begin with a complicated order if you are learning the service. A straightforward purchase from a retailer you already trust is a better test than a large basket containing several products, different shipping times, or items that might be returned separately. A simple first transaction gives you a clearer idea of how the payment option behaves in your own shopping routine.
Screenshots
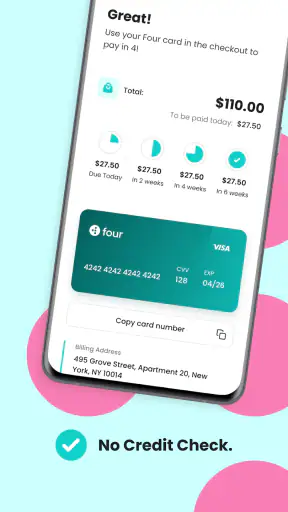
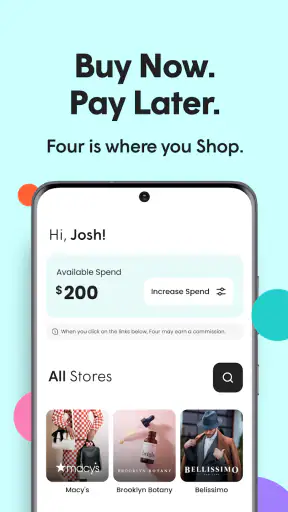
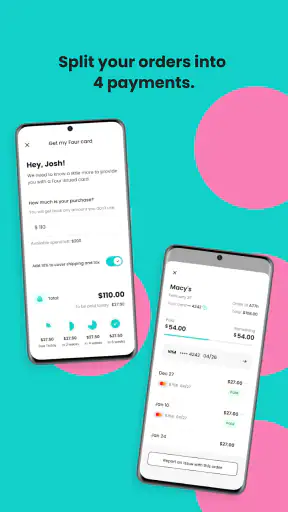
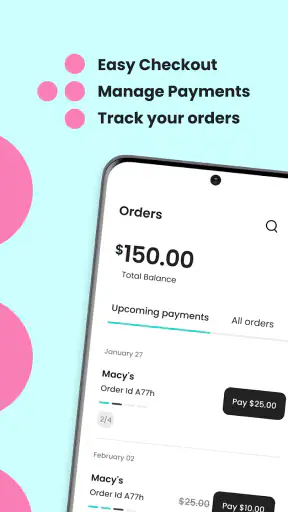
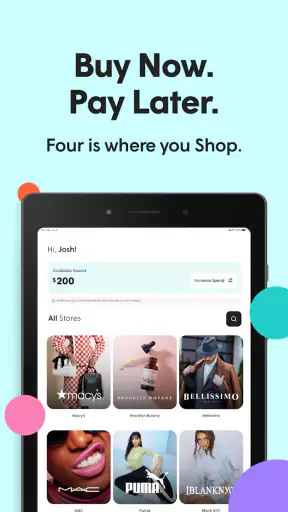
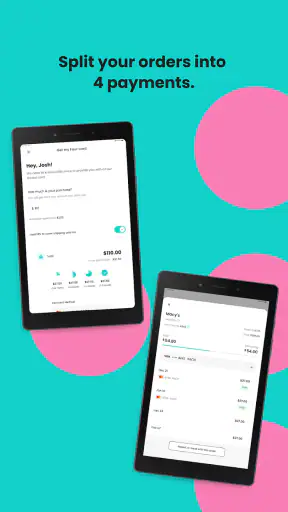
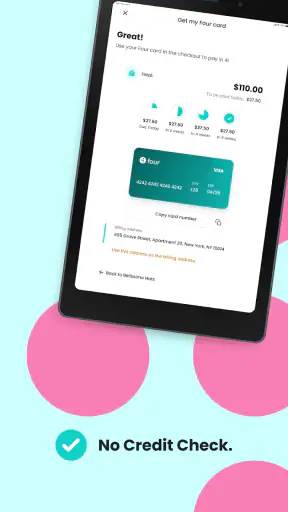
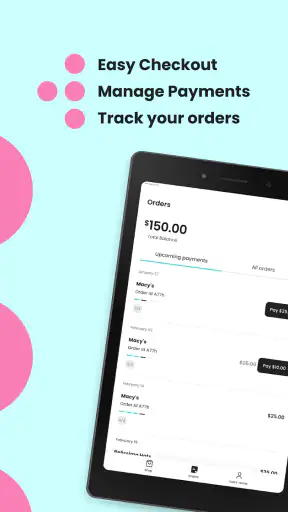
Four’s current version is 1.17.84, and the app supports Android devices from version 6.0 onward. Those details make it accessible to people using older Android phones, but compatibility alone does not guarantee that every device or retailer checkout will feel identical. Keep the app updated when an update is offered through your normal app store, especially if a checkout handoff behaves unexpectedly.
Your first successful action
The first meaningful success is not merely opening Four or creating an account. It is completing a modest, intentional purchase while knowing exactly what happens next. I would choose one item, confirm that Four is presented at checkout, review the payment breakdown, and only then approve the transaction.
When the payment option appears, look beyond the first amount shown. The first payment can feel reassuringly small, but the later scheduled amounts are the part that determines whether the plan fits your month. I recommend taking a screenshot or writing the schedule in a personal budget note, not because the app is necessarily difficult, but because payment plans become harder to remember when several subscriptions and bills compete for attention.
A useful workflow is to place the item in the retailer’s cart, check the ordinary full-payment total, then select Four and compare the arrangement. If the split makes the purchase manageable without changing what you intended to buy, proceed. If the lower initial amount tempts you to add extra items, stop and return to the original basket. This is one of the clearest ways to use the app responsibly.
After completing the order, I would revisit the app and make sure the purchase is visible in the expected place. I would also keep the retailer’s order confirmation, since Four handles the payment arrangement while the retailer remains central to the product, shipping, and order details. Separating those roles helps when something goes wrong: a payment question belongs with Four, while a missing or incorrect item may require the retailer’s support process.
Where new users commonly get confused
The biggest source of confusion is assuming that a payment plan changes the normal rules of shopping. It does not automatically remove the need to check shipping information, product availability, return instructions, or the retailer’s customer-service process. Before confirming an order, I would read the retailer’s policy just as carefully as I would when paying with a card.
Returns deserve particular attention. If you send an item back, do not assume that every part of the payment arrangement will instantly disappear the moment the retailer receives it. Keep the order information and watch for the transaction to be updated. If the retailer says a refund or adjustment has been issued but the payment view does not yet reflect it, contact the appropriate support channel rather than making a second purchase to compensate.
Another point that can trip people up is the difference between an approval screen and a completed order. A payment option may be displayed before the retailer has fully confirmed the purchase. I always look for the final order confirmation from the retailer, not just an indication that Four was selected. This is especially important if the browser or app switches between screens during checkout.
Shoppers also sometimes mistake Four for a general-purpose shopping wallet that replaces their existing payment tools. I would not use it that way. A traditional card remains more straightforward for purchases you can pay in full, while a retailer’s own installment option may be better when it offers clearer terms or is integrated directly with returns and order tracking. Four’s advantage is convenience when it is available and the split fits your budget; it is not automatically the best option for every transaction.
Everyday situations where it makes sense
Imagine that a desk chair breaks while you are working from home. You find a suitable replacement from a retailer that offers Four, and the full cost is manageable but inconvenient in one pay period. In that situation, I can see the appeal: you can focus on a necessary purchase, review a divided schedule, and avoid postponing the replacement solely because of the timing of one paycheck.
A second example is seasonal clothing. If you have already decided what you need and the total is within your planned spending, Four may help distribute the expense. The key is to use it for a defined basket rather than browsing until the payment plan makes an unnecessarily large order appear comfortable.
I would be more cautious with entertainment purchases, trend-driven items, or anything you are considering only because the first payment looks low. Those are the cases where the app can make a want feel like a need. The service is most valuable when it supports a decision you have already made, not when it creates the desire to spend.
Families should also discuss who is responsible for tracking the schedule when a shared device or shared payment method is involved. A divided payment can be easy to forget if the person placing the order is not the person managing the household budget. Four works better when one person clearly records the commitment and checks it against upcoming expenses.
How it compares with ordinary alternatives
Compared with paying by debit or credit card in full, Four adds flexibility but also adds another payment obligation to remember. A full card payment wins for simplicity and immediate closure. Four is preferable only when the structured split provides a real budgeting benefit and you are comfortable managing the later payments.
Compared with a retailer’s own installment plan, Four may be more convenient when you already recognize the service and encounter it across different participating stores. On the other hand, a retailer-native option can feel more seamless because the payment and order information live in one place. I would compare the actual schedule and total commitment rather than choosing based on the brand displayed first.
Compared with a credit card balance, a clearly presented split can be easier to understand than carrying an open-ended balance. That does not mean it should be treated casually. The right choice depends on the terms shown for the particular purchase, your ability to meet every scheduled payment, and how much account management you are willing to do.
Four is therefore best viewed as one tool in a shopping routine, not as a replacement for every payment method. If you prefer one monthly statement, dislike managing multiple due dates, or regularly shop at retailers that do not offer Four, a normal card or direct payment may be less frustrating.
Small habits that make the app easier to use
My first practical habit would be to create a simple note for each active purchase containing the retailer, item, total, and payment dates. This is more useful than relying on memory, particularly if you use installment services more than once. It also makes it easier to spot when a new purchase would overlap with several existing commitments.
My second habit would be to keep the first order deliberately uncomplicated. Avoid combining a new payment plan with a return, exchange, gift purchase, or uncertain delivery unless you already understand how the retailer handles those situations. Learning Four through a clean transaction gives you a reliable baseline.
Third, I would compare the entire checkout screen before accepting anything. Look for the total, the schedule, and the retailer’s order summary. If one of those is unclear, I would stop and investigate rather than assuming the next screen will explain everything. That pause is especially valuable on a small phone display where important text can be easy to overlook.
Finally, I would treat the app’s availability as a convenience, not a reason to change retailers. If another store has a better product, clearer return process, or more suitable full-payment price, those factors should still win. Four can improve how you pay, but it cannot make an unsuitable product or poor shopping experience worthwhile.
Who will appreciate Four, and who should skip it
I think Four is a good match for a first-time buy-now-pay-later user who wants a focused way to divide an online purchase and is willing to monitor the resulting schedule. It is particularly useful for planned expenses that are affordable overall but awkward to pay all at once. The free price also makes it easy to try without paying an upfront app fee.
I would suggest more caution for anyone who already struggles to track recurring bills or frequently forgets payment dates. The convenience of splitting a purchase can become a source of stress when several plans accumulate. Someone who values the simplest possible financial routine may be happier paying in full or using a familiar card statement.
Parents and new adult shoppers should also consider the broader budget, not just whether a single order appears affordable. The age rating is Everyone, but an accessible app still requires mature decision-making. A payment plan is a commitment, and the right question is whether the whole purchase fits comfortably, not whether the first step feels small.
My recommendation after using the full flow
Four makes the most sense when you approach it with a specific purchase already in mind. Install it, set up your account carefully, test it with a simple order from a participating retailer, and record the full schedule before confirming. That path gives a first-time user a concrete success without encouraging unnecessary browsing or overspending.
I like the app’s straightforward purpose and the way it can make a planned online purchase easier to fit into a budget. I also think its limitations are important: retailer availability matters, returns may require patience and coordination, and a divided payment is still a real financial obligation. Those are not reasons to dismiss Four, but they are reasons to use it deliberately.
For shoppers who want flexibility and can keep accurate track of what they owe, Four is worth considering. For anyone looking for a universal wallet, a marketplace full of products, or a way to make unaffordable purchases harmless, it is the wrong tool. My recommendation is to use Four as a controlled checkout option, compare it with paying in full, and approve an order only when the complete commitment feels comfortable.
Four | Buy Now, Pay Later FAQ
What is Four, and how does its buy now, pay later service work?
Four is a buy now, pay later service that allows eligible shoppers to split the cost of a purchase into several scheduled payments rather than paying the full amount immediately. During checkout, the app typically shows the payment plan, installment amounts, and due dates before you confirm. Approval, available plans, and purchase limits can vary depending on your account, retailer, and eligibility assessment.
Does Four charge interest, fees, or other costs?
Four commonly promotes installment plans with no traditional interest when payments are made according to the agreed schedule, but users should carefully review the specific terms shown at checkout. Some transactions, retailers, or account situations may involve fees, and late or missed payments can have consequences. Before accepting a plan, check the total repayment amount, payment dates, and any applicable charges in the app.
What happens if I miss a Four payment?
If you miss a scheduled payment, Four may retry the payment method connected to your account and could apply restrictions, fees, or other consequences depending on its current terms and your location. A missed payment may also prevent you from making additional purchases until the account is brought up to date. Contact Four support promptly if you expect a payment problem or need help understanding your options.
Can I use Four for every online or in-store purchase?
Four is not necessarily available for every merchant, product, or purchase amount. You generally need to shop with a participating retailer and meet Four’s eligibility requirements at the time of checkout. The service may also exclude certain categories, limit transaction values, or offer different payment plans depending on the merchant. Always confirm that Four appears as an available payment option before completing your order.
What should I know about refunds and returns when using Four?
Returns and refunds are usually handled first through the retailer’s own return policy, while Four adjusts the payment plan after the merchant confirms the refund. Until the refund is processed, scheduled installments may still be attempted, so do not assume that returning an item automatically cancels upcoming payments. Keep your order information, follow the retailer’s instructions, and monitor the Four app for updated balances and payment dates.